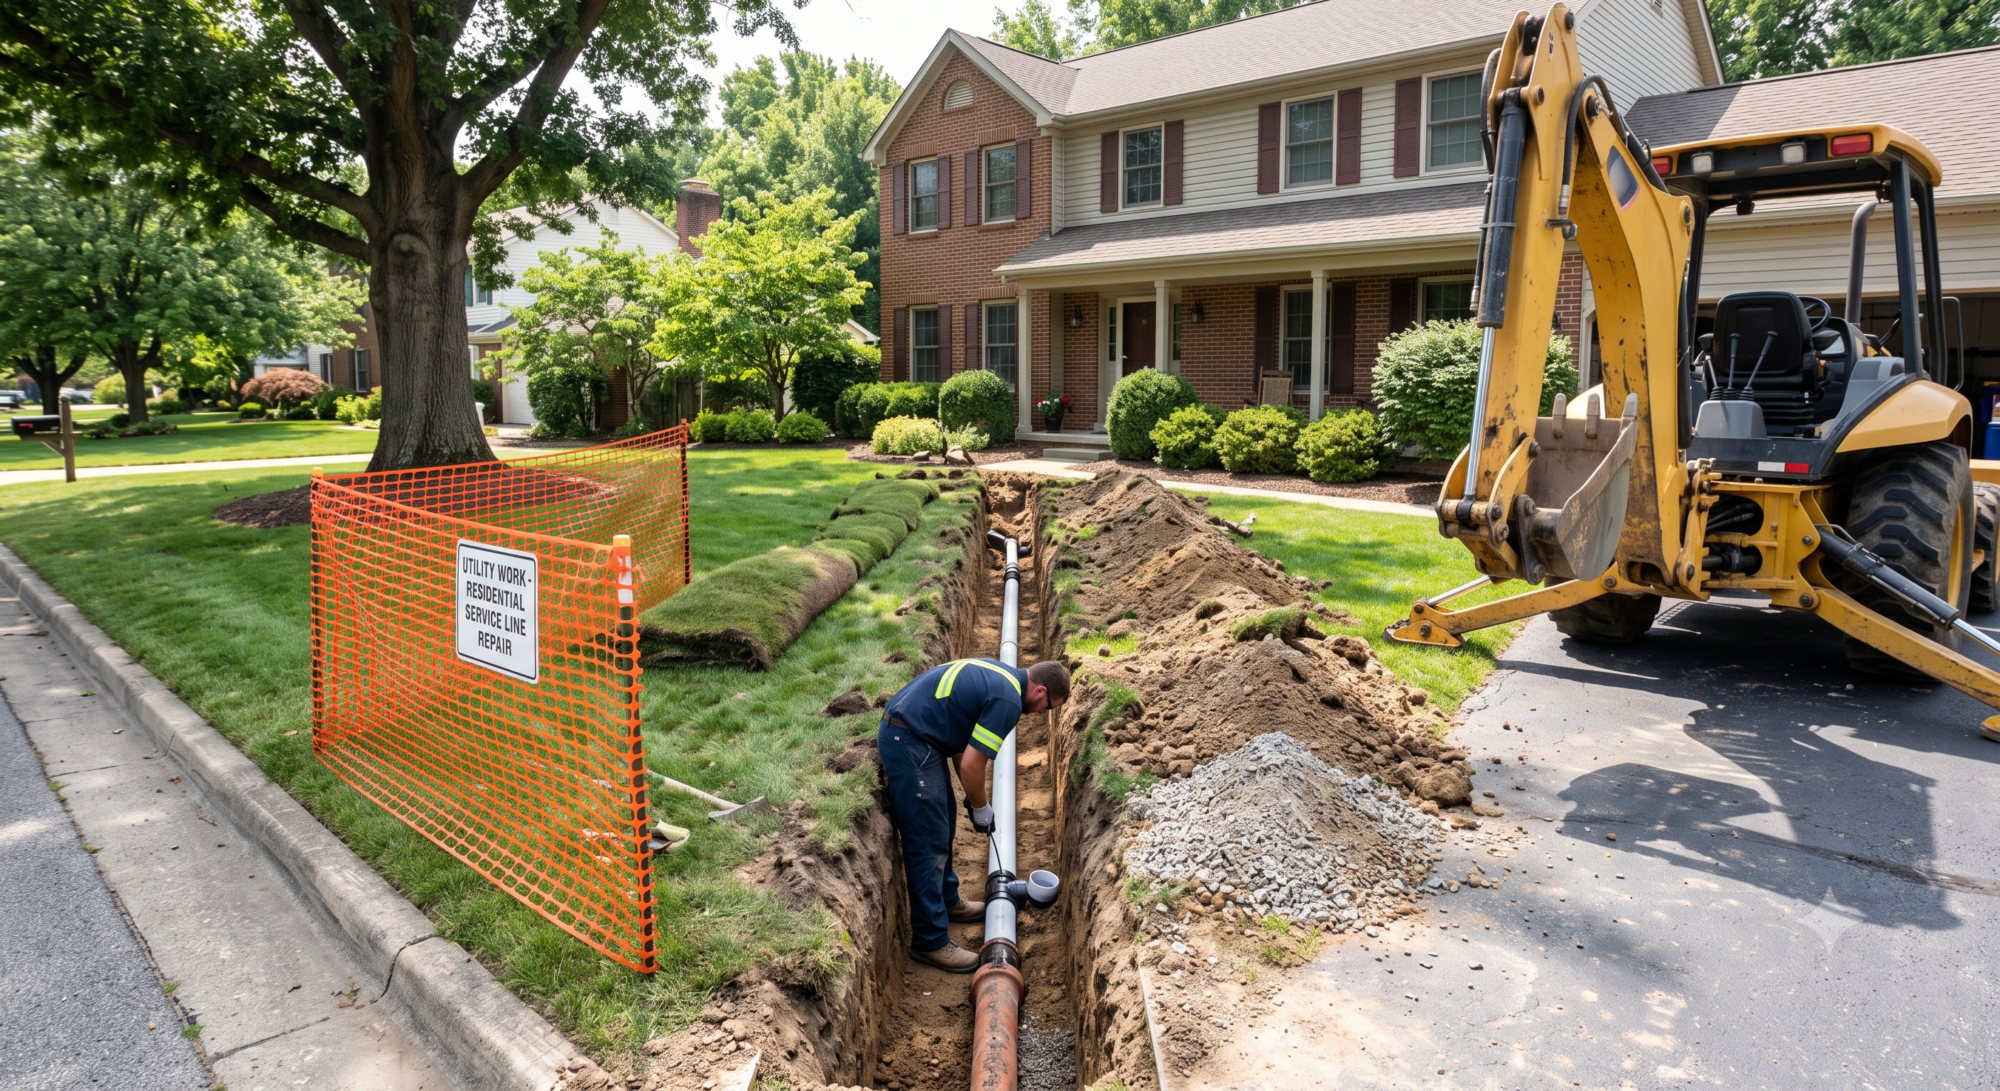
Imagine waking up to a soggy, foul-smelling lawn, only to discover your main sewer pipe collapsed. You call the city, but they drop a truth bomb: The line collapsed on your side of the property line, so the fix is on you.
Then comes the plumber’s estimate: $6,000 to dig up the yard, replace the pipe, and patch the driveway.
When you file a claim on your standard homeowners insurance, you’re met with another shock—it’s denied. Standard HO-3 policies rarely cover wear and tear, tree root damage, or gradual decay on utility lines outside the home.
Enter the Service Line Endorsement: a low-cost add-on that bridges one of the biggest coverage gaps in modern homeownership.
What Is a Service Line Endorsement?
A Service Line Endorsement (sometimes called Underground Utility Line Coverage) is an optional rider you can add to your existing homeowners policy. It pays to repair or replace damaged underground utility lines that run from the street to your house.
What Lines Are Covered?
-
Water Supply Lines (freshwater coming into the house)
-
Sewer & Waste Lines (wastewater leaving your home)
-
Underground Power Cables
-
Natural Gas & Fuel Pipes
-
Data Lines (fiber optic, cable TV, and internet lines)
Note: Standalone, self-contained systems like septic tanks or private water wells are generally excluded under this specific endorsement, as they don’t connect to a public utility.
What Types of Damage Does It Cover?
Standard insurance policies exclude “wear and tear,” but service line endorsements are designed specifically for it. Coverage typically kicks in for losses caused by:
-
Tree Root Intrusion: Roots breaking into, clogging, or collapsing pipes.
-
Rust & Corrosion: Pipes or wiring degrading due to age or soil chemistry.
-
Ground Movement & Freezing: Soil shifting, freezing-thawing cycles, or heavy equipment driving over the lawn.
-
Mechanical Breakdown: Sudden internal failures of underground wiring or conduits.
What Expenses Does the Policy Pay For?
Fixing an underground line isn’t just about paying for a 10-foot piece of PVC pipe; the labor to get to it is where costs skyrocket. A service line endorsement covers:
-
Excavation Costs: Digging up your lawn, garden, or driveway to reach the pipe.
-
Line Repair or Replacement: The actual materials and plumbing/electrical labor.
-
Property Restoration: Backfilling the trench, re-seeding grass, or replacing damaged concrete.
-
Loss of Use: Hotel stays if a broken gas or sewer line forces you out of your house while repairs happen.
By the Numbers: Why the Math Makes Sense
The return on investment for this rider is hard to beat in the insurance world.
Coverage FeatureTypical Endorsement DetailsAverage Annual Premium$30 – $50 / year (around $3–$4 a month)Typical Coverage Limit$10,000 – $20,000 per occurrenceStandard Deductible$500Average Out-of-Pocket Claim$3,000 – $8,000 without coverage
The Real-World Scenario
-
A 40-year-old terracotta sewer pipe collapses under your yard due to tree root growth.
-
The total repair, excavation, and lawn re-sodding costs $6,500.
-
Without Endorsement: You pay $6,500 out of pocket.
-
With Endorsement: You pay your $500 deductible. Insurance handles the remaining $6,000.
Endorsement vs. Utility Protection Plans: What’s the Difference?
You’ve likely received mailers from third-party utility companies or home warranty programs offering “Water Line Protection” for $10–$15 per month.
-
Utility Protection Plans: Usually cover only one line (e.g., just water OR just sewer), cost $120–$180 a year, and often have strict caps or exclusions on excavation and property restoration.
-
Insurance Service Line Endorsements: Cover all underground lines on your property under one umbrella for around $30–$50 a year.
Going through your homeowners policy endorsement is almost always significantly cheaper and far more comprehensive.
Should You Add It to Your Policy?
You should strongly consider adding this coverage if:
-
Your home is over 15–20 years old (aging pipes are prone to sudden breakdown).
-
You have mature trees growing near the front lawn or utility path.
-
You live in an area with harsh winter freezes or expansive clay soil.
-
You don’t have $5,000+ sitting in an emergency savings fund reserved solely for sudden home repairs.
How to Get Covered
Adding this protection is easy. Call your insurance agent or log into your portal and ask: “Do you offer an Underground Service Line Endorsement, and what are the limits?” In most cases, it can be added instantly for just a few extra dollars on your monthly mortgage or insurance payment.